Investor & Expat Advice
Buying a KL Condo as a Foreigner in 2026: The Real Costs
RM1 million minimum, 8% stamp duty, state consent and RPGT — what a foreign buyer actually pays for a Kuala Lumpur condo in 2026, with a worked RM1.5 million example.
By Jerry See (REN 11499) · 26 September 2026 · 3 min read

Photo: Jermaine Ee / Unsplash
Foreigners can buy a condo in Kuala Lumpur. The catch is the cash you need on top of the price. Since 1 January 2026, foreign buyers pay a flat 8% stamp duty on the transfer — double the 4% flat rate that applied in 2025 — and banks usually lend foreigners only 60–70% of the value.
In practice, that means a foreign buyer should plan to have roughly half the purchase price in cash on day one. Here is how the numbers work.
The rules in 30 seconds
- Minimum price in Kuala Lumpur: RM1,000,000 for foreign individuals buying residential property. Other states set their own thresholds — Selangor is RM2 million in most zones.
- State consent is required. Every foreign purchase needs approval from the land authority. Your lawyer applies for it; allow about 1–3 months.
- Some units are off-limits. Bumiputera-reserved units and low-cost housing cannot be sold to foreigners, and landed homes are heavily restricted.
- Stamp duty on the transfer is a flat 8% for non-citizens and foreign-owned companies (Malaysians pay a tiered 1–4%). Malaysian permanent residents are generally treated like citizens — confirm this with your lawyer.
Worked example: a RM1.5 million condo in Mont Kiara
Assume a foreign buyer purchases a completed Mont Kiara condo at RM1,500,000 with a 60% bank loan (RM900,000).
| Cost item | How it is calculated | Approx. amount |
|---|---|---|
| Down payment | 40% of price | RM600,000 |
| Stamp duty on transfer (MOT) | Flat 8% of RM1.5m | RM120,000 |
| Stamp duty on loan agreement | 0.5% of RM900k | RM4,500 |
| Legal fees — sale & purchase | Solicitors' scale, plus 8% SST | ~RM17,500 |
| Legal fees — loan documents | Solicitors' scale, plus 8% SST | ~RM11,000 |
| State consent, searches, disbursements | Varies by case | Ask your lawyer |
| Cash needed upfront | ~RM753,000+ |
For comparison, a Malaysian buying the same unit would pay about RM44,000 in transfer stamp duty instead of RM120,000.
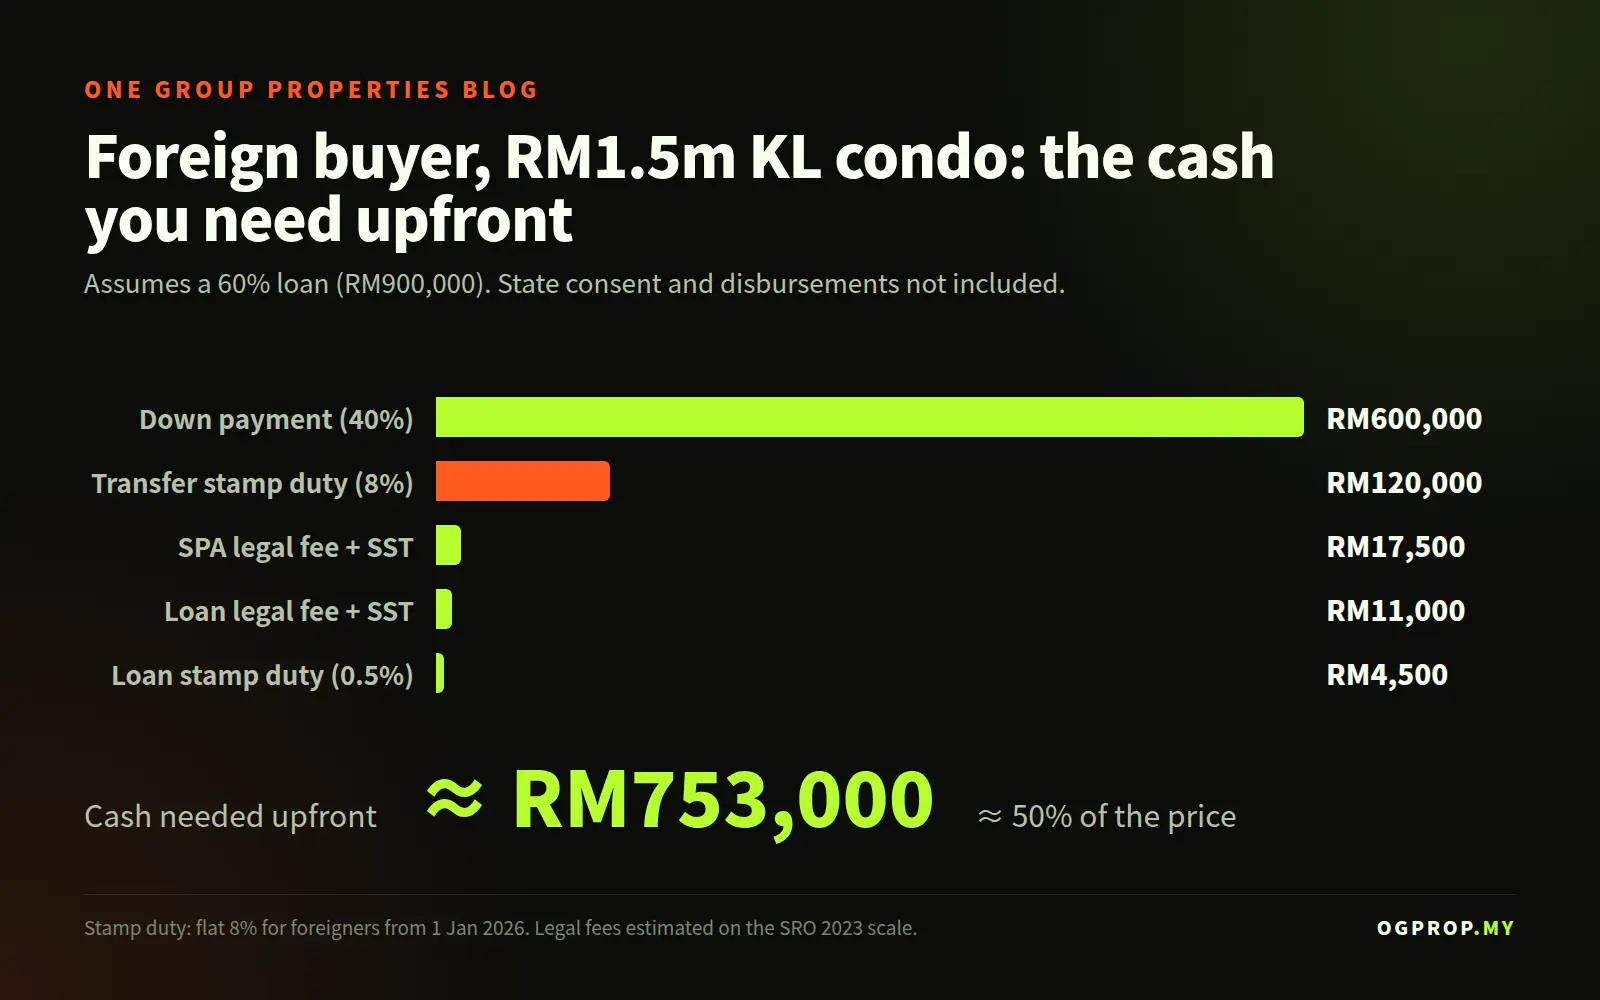
Rule of thumb: for a KL condo, a foreign buyer should budget about 50% of the price in cash if borrowing 60%, or about 40% if the bank lends 70%.
Getting a loan as a foreigner
Most Malaysian banks will lend to foreigners, but on tighter terms than for locals:
- Margin of finance is usually 60–70%, sometimes lower depending on your income country and the bank.
- Banks look for verifiable income, and many prefer buyers with Malaysian income, an MM2H visa or an employment pass.
- Get a loan pre-approval before paying the booking fee. It is the single best way to avoid losing a deposit.
Selling later: RPGT for foreigners
When you sell, Real Property Gains Tax (RPGT) applies to the gain. The rates for non-citizens are higher than for Malaysians:
| Disposal | Non-citizens | Malaysian citizens / PRs |
|---|---|---|
| Within years 1–5 | 30% | 30% (yr 1–3), 20% (yr 4), 15% (yr 5) |
| Year 6 onwards | 10% | 0% |
The buyer also holds back 7% of the price from a foreign seller (3% for Malaysians) and pays it to LHDN, until the RPGT return is settled. Anyone buying to flip within five years should run these numbers carefully.
A sensible order of steps
- Confirm your budget clears the RM1 million KL threshold and covers the ~50% cash outlay.
- Get a loan pre-approval from a bank that lends to your profile.
- Shortlist units that are open to foreigners — not Bumiputera-reserved, above the threshold.
- Pay the booking fee (usually 2–3%) and sign the SPA through your lawyer.
- Your lawyer applies for state consent; the transfer completes once it is granted.
If you are comparing areas, start with our Mont Kiara and KL City Centre guides, or browse current property listings.
This article is general information, not legal, tax or financial advice. Rules and rates change — confirm with your lawyer, bank or tax adviser before you commit.
Have a question about this?
WhatsApp our team for a straight answer, a shortlist or a viewing.
WhatsApp UsMore articles

Investor & Expat Advice
Solaris Parq Mont Kiara: Rent or Buy? Costs Compared (2026)
Residensi Solaris Parq, Mont Kiara: current asking rents (RM3,000–RM9,500) and prices (RM1.25m–RM1.95m) on ogprop.my, and what renting vs buying really costs.
8 October 2026 · 6 min read

Investor & Expat Advice
Mont Kiara vs Damansara Heights vs KLCC: Where Should Expats Live in KL?
A practical comparison of KL's three favourite expat addresses — lifestyle, schools, commute and the rents we are seeing — to help you pick the right neighbourhood before you view.
26 September 2026 · 2 min read

Area & Condo Guides
Mont Kiara Rents by Building (2026): What Each Condo Asks per Month
Current asking rents at Solaris Parq, Jendela Residences, Kami and Arcoris SOHO in Mont Kiara, by size and bedroom count, from the 25 units listed on ogprop.my.
17 October 2026 · 5 min read